 Skip to content
If you have been watching mortgage rates tick back up, I already know the question sitting in the back of your mind.
Should we just hit pause and wait for them to come down?
I am going to be straight with you. Rates are moving the wrong direction right now, and nothing you do this week changes that.
But that is only half of the story. The rate a lender quotes you is not simply the market's number. It gets built from pieces, and three of those pieces are sitting in your hands.
I want to walk you through what is pushing rates up, and the three things that shape the rate you actually get.
You cannot control where the market sends mortgage rates. You can control the credit profile, loan structure, and home choice that help determine the rate and payment attached to your file.
First, Why Rates Are Moving the Way They Are.
Mortgage rates do not answer to one thing.
They respond to what is happening overseas, economic data, inflation numbers, oil prices, bond-market expectations, and Federal Reserve policy. On September 16, the Federal Reserve raised the federal funds target range by a quarter point, its first increase in more than three years. The Fed does not set your mortgage rate directly, but its decisions can influence the longer-term rates and expectations that feed mortgage pricing.
If you want to understand more of the mechanics underneath the headline rate, read what the spread between the 10-year Treasury and mortgage rates can tell you. That spread is one reason mortgage rates do not move one-for-one with the Fed.
And this is bigger than one meeting. Danielle Hale, Chief Economist at Realtor.com, told Keeping Current Matters that the pressure on mortgage rates was already there before the Fed acted and did not appear to be letting up.
Here Is What the Data Is Showing Right Now.
Mortgage News Daily's daily data shows rates climbing through 2026, from roughly the low-6% range early in the year to above 7% in September.
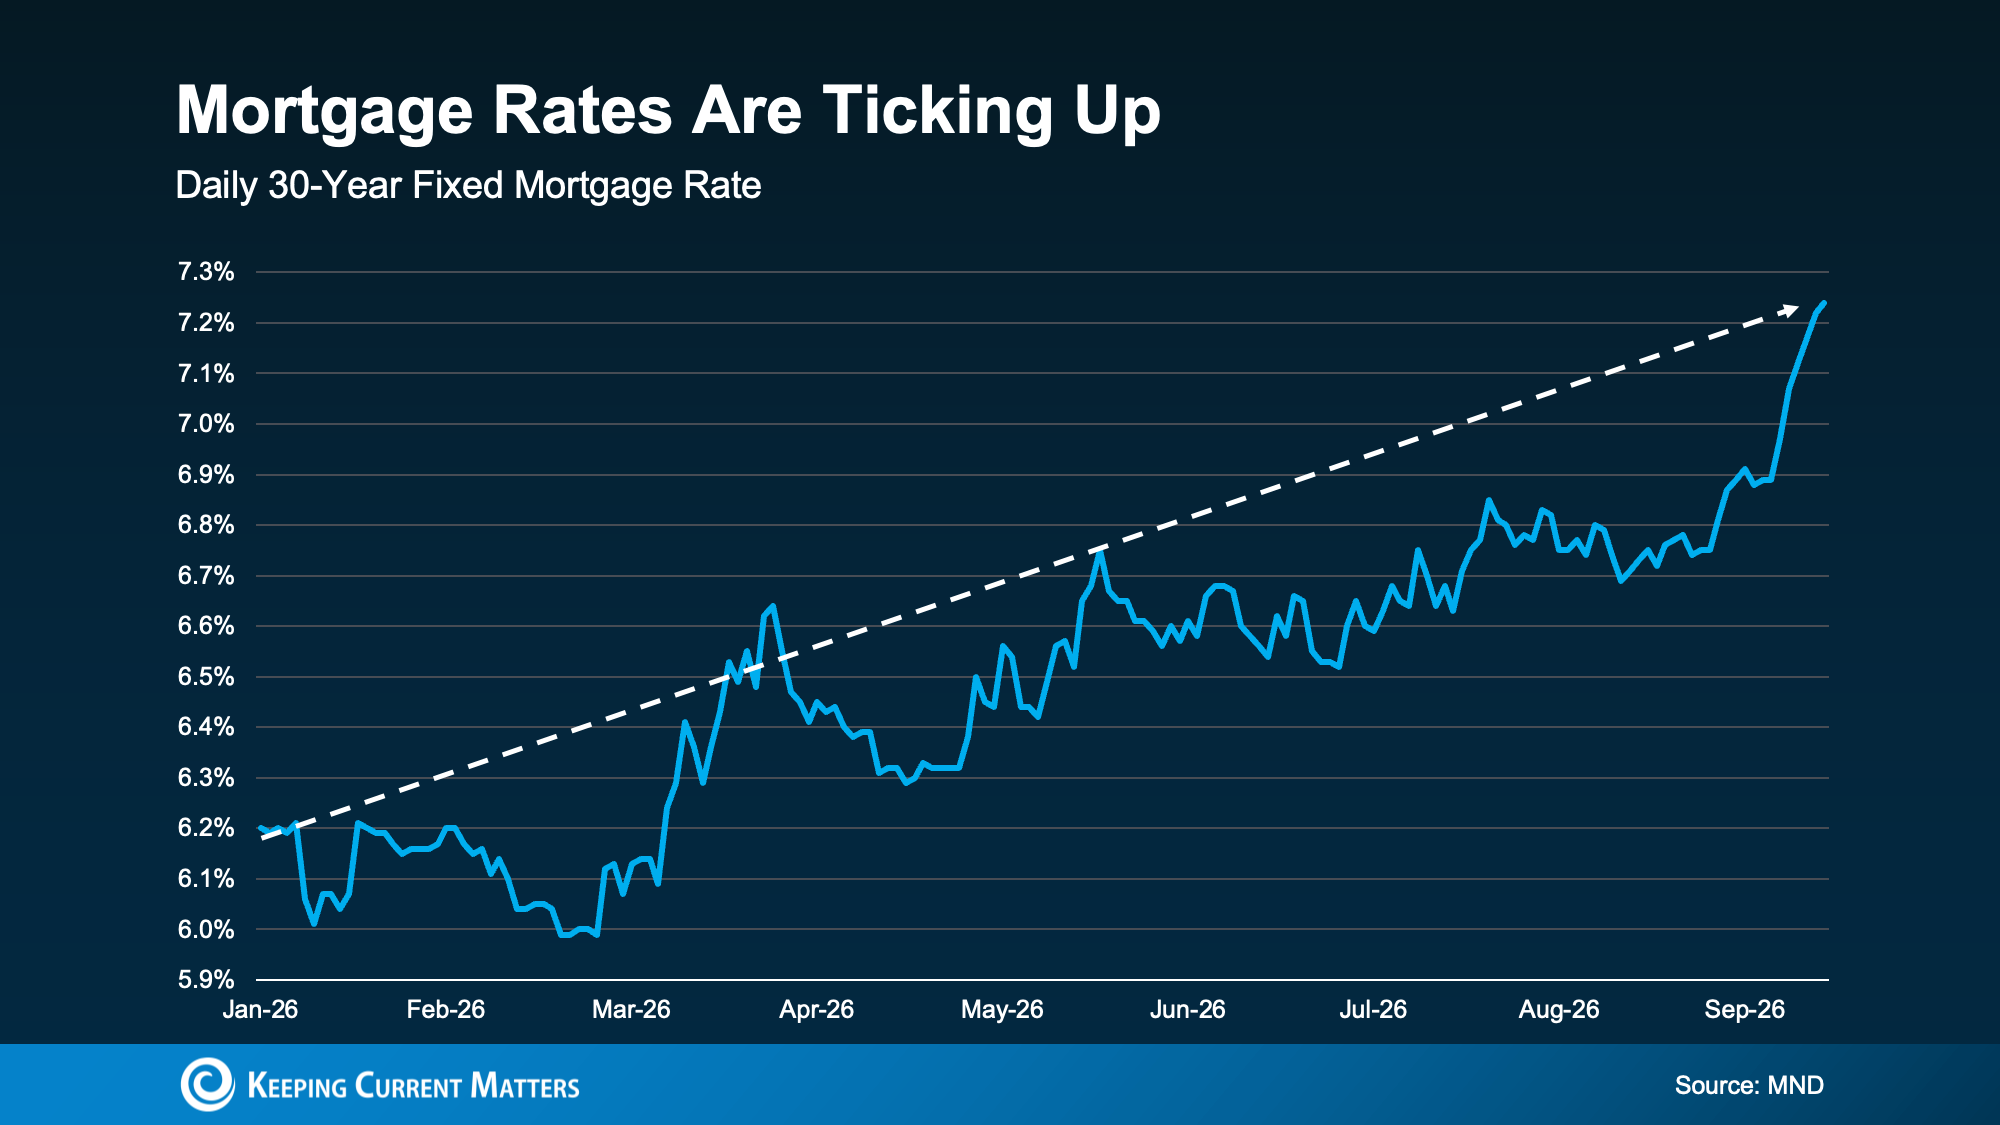
Depending on who is measuring, the national 30-year fixed average is sitting around 7%. Freddie Mac's weekly survey put it at 6.76% for the week ending September 10. Bankrate's national average reached 7.06% by September 17.
Read that again. Two respected sources, two different numbers, and neither one is necessarily the rate a lender is going to quote you.
That is the point. A national average is a headline. Your rate is a quote, and the quote is built from your file.
Three areas matter here: your credit, your loan, and the home you choose.
What the Headlines Always Leave Out.
Every headline about rates is about the one thing you cannot touch.
You cannot control the Fed. You cannot control oil prices, inflation, Treasury yields, or what happens overseas. A story that only talks about those things leaves you one option, which is to sit and wait.
Waiting is not a plan. It is handing your timeline to a market that does not know you exist.
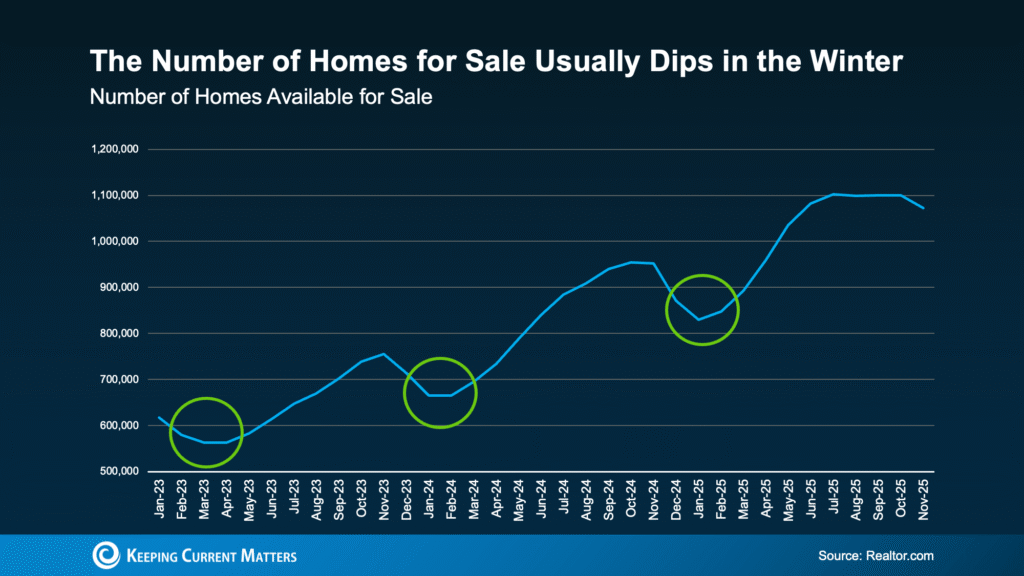
And waiting for lower rates can come with a tradeoff. In some markets, higher rates are also helping keep more homes available, which means waiting for rates to fall can actually mean facing more competition later.
Meanwhile, the pieces that shape your quote are sitting right in front of you: your score, your loan, and your home. A lot of buyers do not look at them until a lender forces the issue.
What This Means For Your Plan.
Stop asking only where rates are going. Start working the three things that help decide the rate you get.
1. Work on your credit score.
Your credit profile can materially affect mortgage pricing. Freddie Mac's consumer guidance says stronger credit generally gives borrowers more options, including better loan terms and lower rates.
Under Rule 3 in our system, use only 10% of your available credit limit and pay the balance down every month. On a $10,000 limit, that means keeping the reported balance under roughly $1,000 and paying responsibly.
Under Rule 7, consider asking existing card issuers for higher limits without increasing your spending, avoid unnecessary store cards, and keep a small set of major cards clean and well managed.
Do that, and your credit is working for you before you ever sit down with a lender. If you are not sure where your score stands, that is your first conversation with a trusted mortgage professional. Ask about timing before you close accounts, open new credit, move large balances, or make another major credit change right before applying.
2. Explore your loan options.
Conventional, FHA, VA, and USDA loans each come with different requirements, pricing, mortgage-insurance structures, and tradeoffs. Your term, whether 15, 20, or 30 years, affects both your payment and the total interest you can pay over time. Fixed versus adjustable determines whether the rate remains stable or can move later.
This is where the numbers have to hold. Under Rule 8, our household planning target is to keep total DTI at 35% or below when possible. Under Rule 9, keep total housing cost, including principal, interest, taxes, and insurance, at or near 30% of gross monthly income as a planning target.
You can test those numbers before you talk yourself into a house by using the DTI calculator. It lets you see how purchase price, down payment, rate, housing expenses, and monthly debts interact.
A mortgage payment you can afford today is not always one you can sustain for 30 years. That matters most on an adjustable loan. A starting rate that looks lower is only a bargain if you can carry the payment after it changes.
Under Rule 13, the long-term goal is to pay off the primary mortgage faster when the rest of the plan supports it, either through a shorter term or extra principal. Shorter terms often come with lower rates and less total interest, but the monthly payment is higher, so run it through the housing-payment rule first.
Then compare more than one quote. Same borrower, same property, same day, and two lenders can still price a loan differently because of margins, points, credits, and program execution.
3. Consider a newly built home.
Another path to a lower rate may come from the home itself. Many builders are using mortgage-rate buydowns and financing incentives to help move inventory.
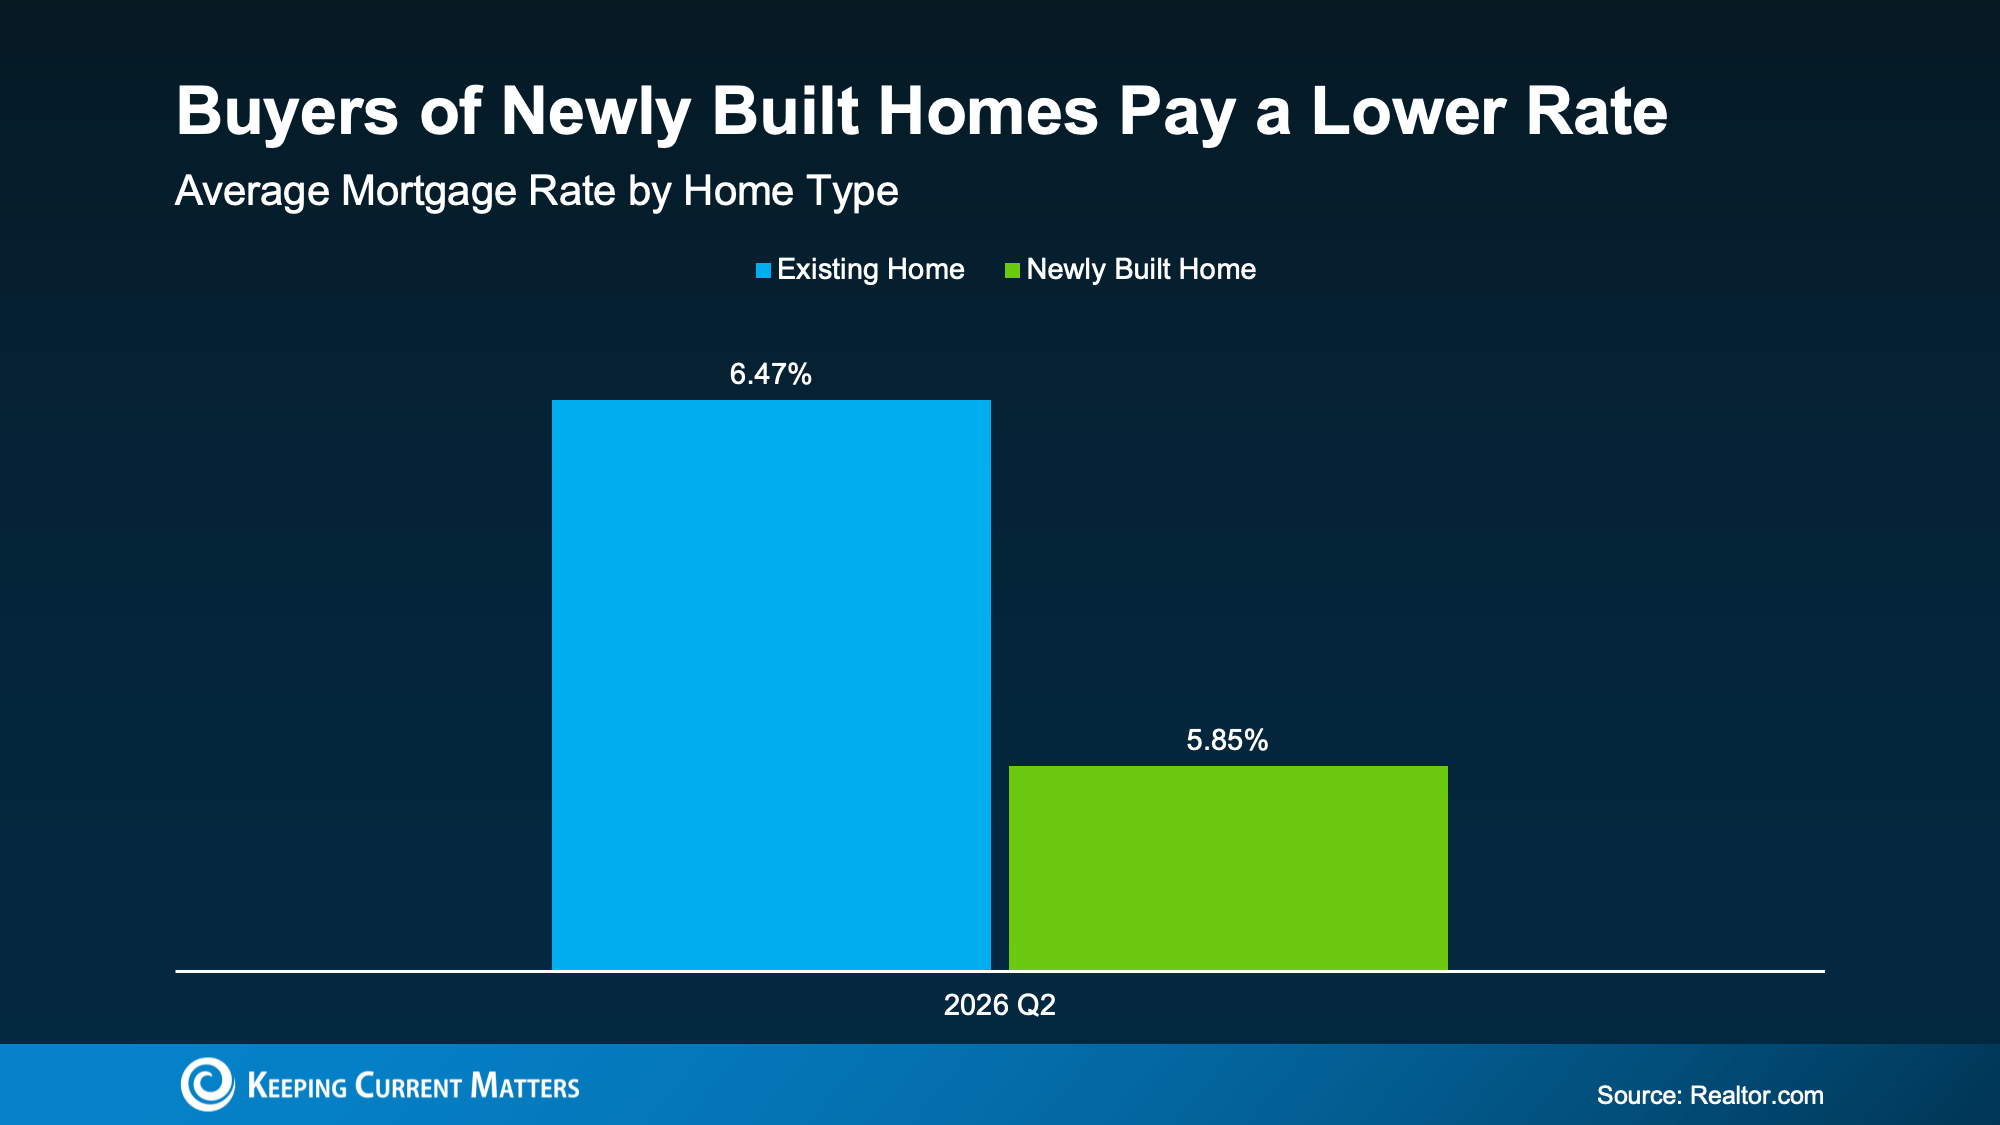
If a lower rate is your goal, ask your agent to show you new-build communities offering incentives, and compare the entire transaction. My recent breakdown on new construction pricing, incentives, and rate buydowns explains why the builder offer should be compared with a resale on the same page.
Bring your own agent before you walk into a model home, not after. The sales representative in the model works for the builder.
Then ask three questions: Is the rate buydown permanent or temporary? What does the payment look like if the buydown expires? Does the incentive require the builder's lender, and how does that lender's complete quote compare with another lender's?
A lower rate only helps if the payment it creates still fits your budget.
Compare your credit, loan choices, DTI, and payment before you wait on the market.
We can review your current profile, run more than one loan structure, compare new construction with resale, and see what actually changes your monthly number.
Talk With PatThe Question You Should Be Asking Together Right Now.
Not, when will rates come down?
The better question is: which of these three can we improve before we apply, and what is each one worth to our monthly payment?
My wife and I have watched rates run through every kind of cycle in 34 years of marriage and real estate. The couples who came out ahead were never the ones who called the Fed right. They were the ones who worked the numbers they could control and moved when their file was ready.
Know the scores a mortgage lender will actually use, the balances reporting on revolving accounts, and whether any changes should happen before an application.
Know the monthly debt load and the complete housing payment you are willing to carry before you decide how much house to buy.
Put resale, new construction, builder credits, rate buydowns, points, down payment, taxes, insurance, and reserves on the same page.
Put it on the agenda for your next Money Meeting. Rule 10 says sit down together at least twice a month. Pull your score. Look at your cards. Write down your DTI and your target housing payment. Then talk to a trusted lender.
You cannot move the market. You can absolutely move your file.
Bottom Line
Mortgage rates are climbing again, and the market forces behind that move are outside your control. But the rate attached to your mortgage is not determined by the headline alone.
Your credit profile, the loan you choose, and the property or builder financing you pursue can all change the quote and the monthly payment.
Work those three before you let a national average decide whether you are ready to buy.
Educational disclosure: This article is for general educational purposes and is not individualized mortgage, financial, legal, tax, insurance, credit, investment, appraisal, construction, or real estate advice. Mortgage rates, pricing adjustments, loan availability, credit-score requirements, debt-to-income limits, mortgage insurance, builder incentives, rate buydowns, points, lender credits, and qualification standards vary by borrower, property, occupancy, loan program, lender, market, and timing. National average rates are not a quote or guarantee. Adjustable-rate mortgages can change after the initial fixed period, and temporary buydowns do not permanently reduce the note rate. Review current written loan terms and builder incentives with the appropriate licensed professionals before making a decision.
Reference sources: Keeping Current Matters — “3 Things You Can Actually Control About Your Mortgage Rate Right Now”, September 21, 2026. Additional rate and Federal Reserve figures referenced above were verified against The Close — “Fed Raises Rates for First Time in 3 Years as Mortgage Rates Hover Near 7%”, September 17, 2026.