You Think a Buyer Backing Out Is a Reason to Wait. Here Is the Problem With That Plan.
Canceled contracts are up, and some sellers are holding off because of it. Most deals still close. Here is how to get ahead of a buyer backing out before you list.
 By Pat Collins
7 min read
Updated October 29, 2026
vs closed
Most deals still close. Prepared ones close cleaner.
You have heard the stories. A buyer signs, the house goes pending, and three weeks later the deal falls apart. So you decide to hold off on listing until the market feels safer.
I understand the fear. Waiting does not fix it.
The risk of a buyer backing out is real, and it is up this year. It is also mostly predictable. The three biggest reasons deals fall apart can be spotted before you ever accept an offer.
I want to show you what is driving canceled contracts right now, why buyers actually walk, and how I look at an offer through a lender’s eyes before you say yes.
Most home sales still close. When a buyer backs out, it is usually over the inspection, the financing, or a home they could not sell. Get ahead of all three before you list, and the fear stops running your timeline.
First, Why the Risk of a Buyer Backing Out Is Rising.
Two things changed at the same time.
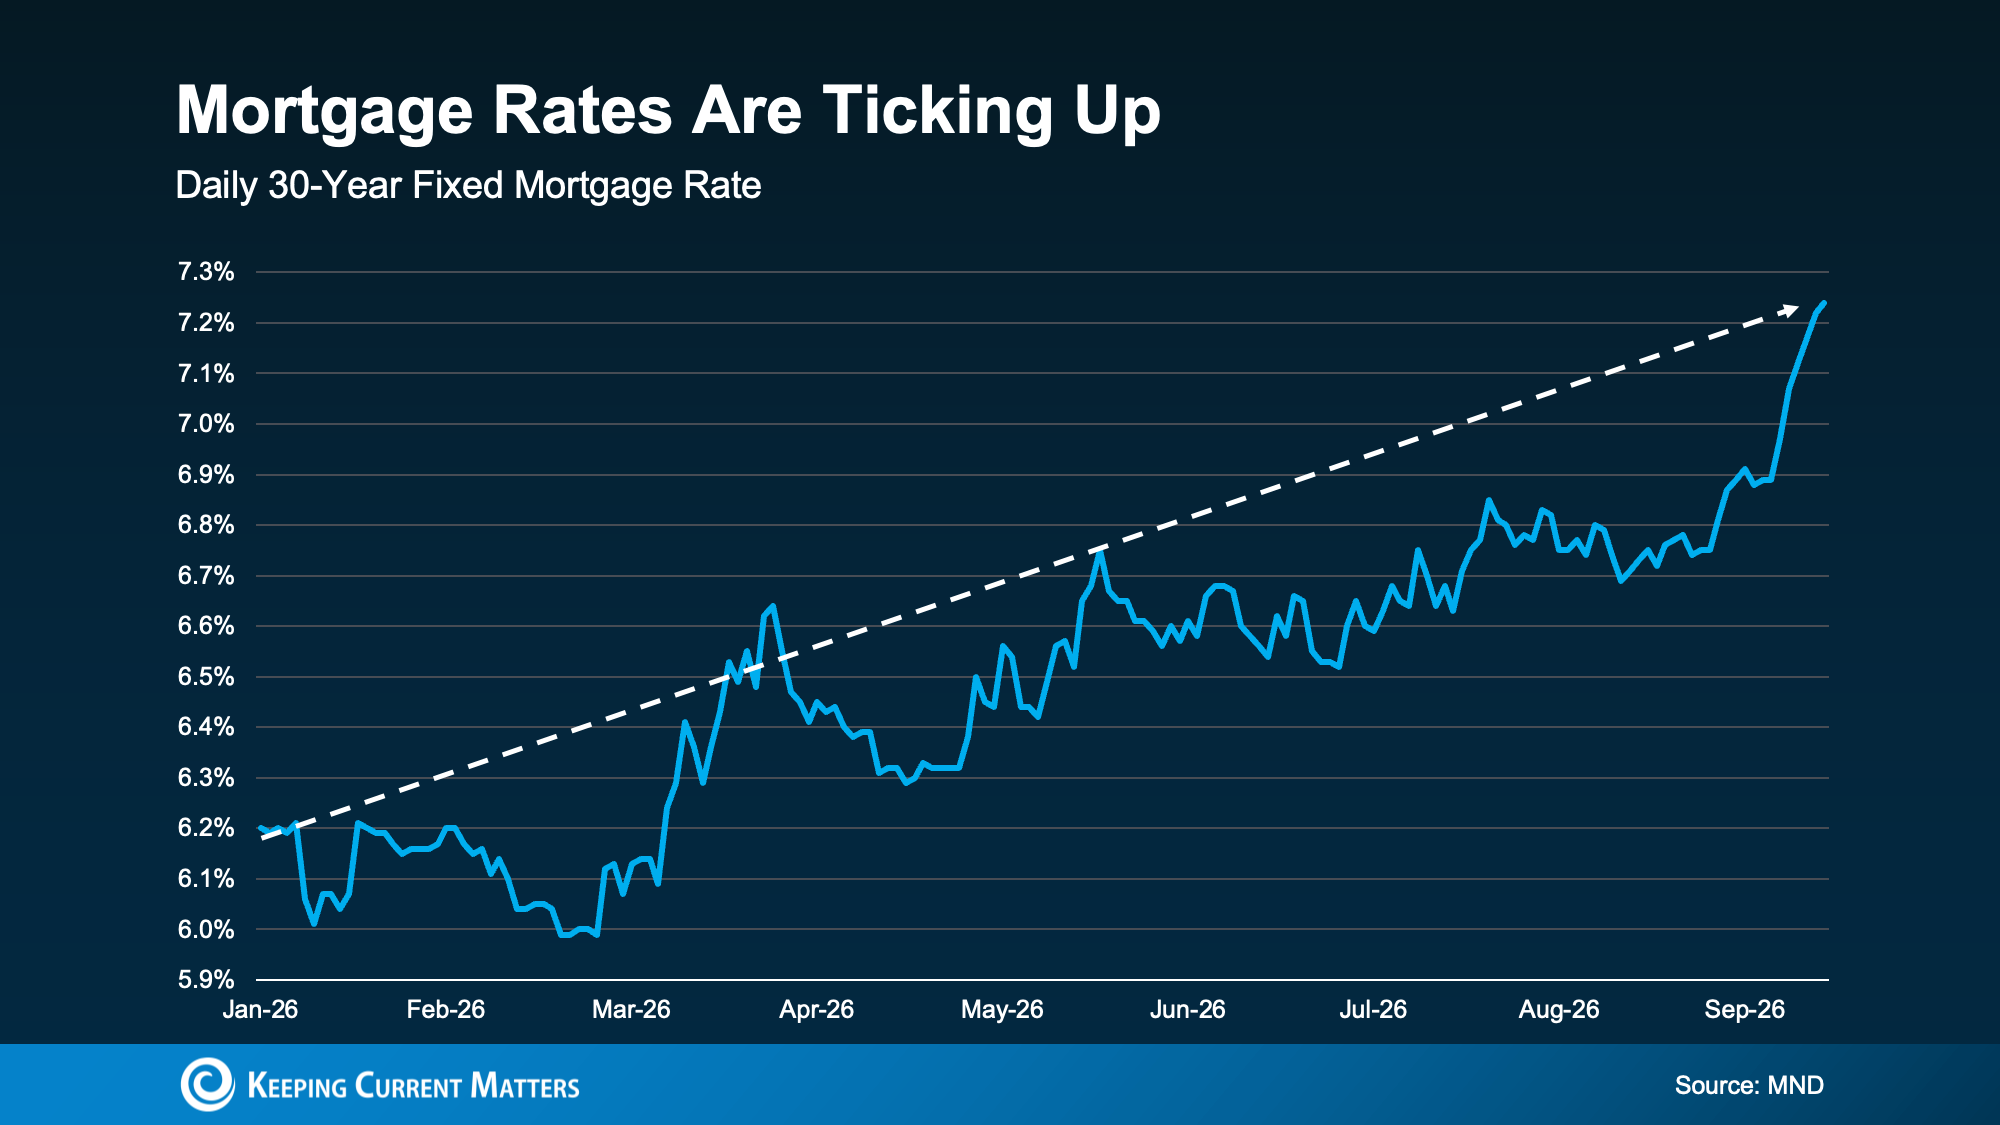
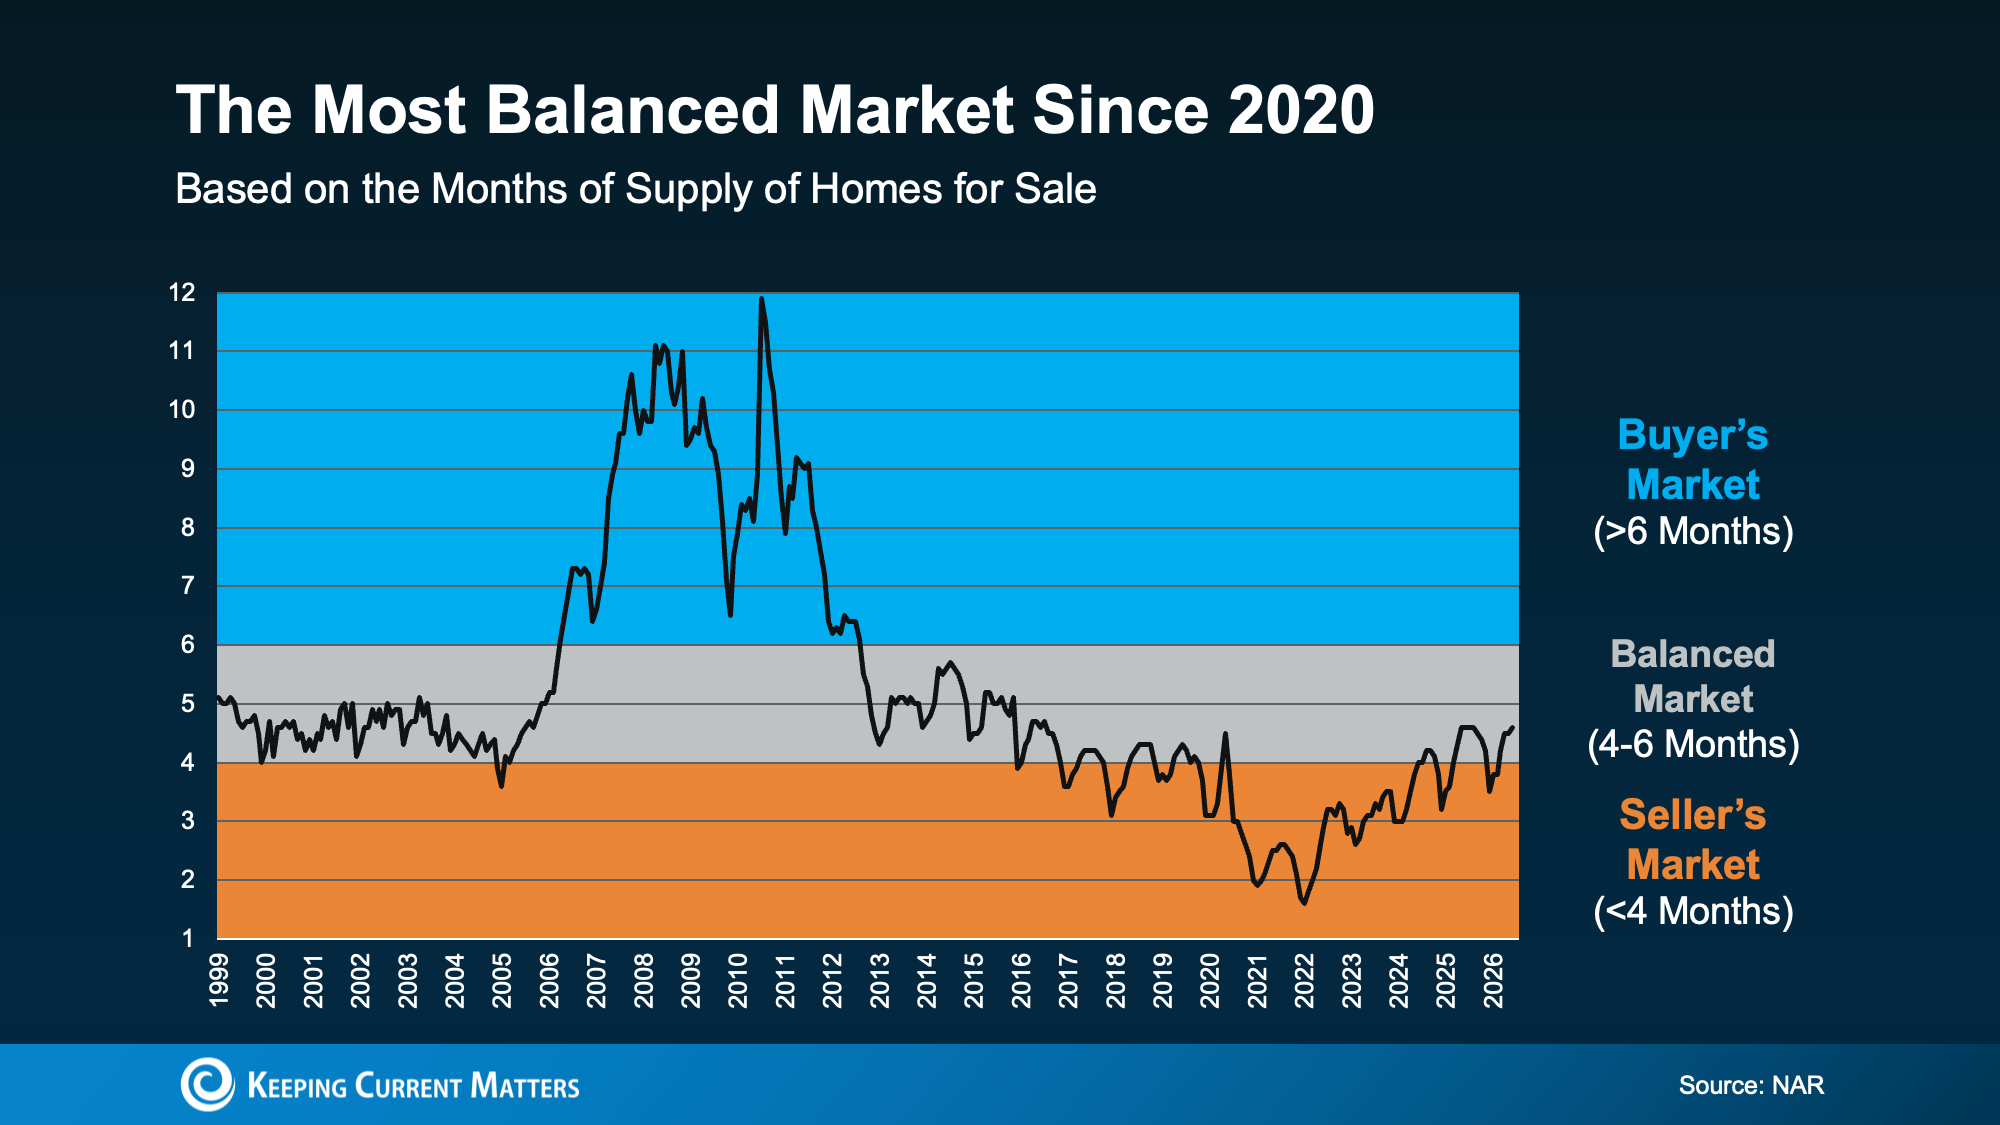
Rates went up. Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed at 7.32% for the week ending October 22, 2026. A year earlier, it was 6.19%.
That move stretches budgets. Cotality said it plainly in its September 24, 2026 market report: “Rising mortgage rates have pushed buyers without rate locks beyond their affordability boundaries.”
And buyers have more choices. With more homes for sale, walking away from one house is easier. Redfin noted that more options make buyers “more likely to walk away if an inspection uncovers problems,” as cited by Keeping Current Matters.
Tighter budgets. More options. That is the recipe for more canceled contracts.
Here Is What the Data Is Showing Right Now.
Cancellations are up.
Cotality reported that nearly 12% of June’s contracts had not closed by the 60-day mark in August. That was the highest August cancellation rate in 5 years, and 1.3 percentage points higher than August 2025.
Keeping Current Matters puts the share of sales that hit this snag at 10% to 15%.
Now flip that number around. Most contracts still make it to the closing table.
The more useful number is why buyers walk. In September 2025, Redfin surveyed 443 of its agents who had dealt with a canceled deal in the prior 3 months.
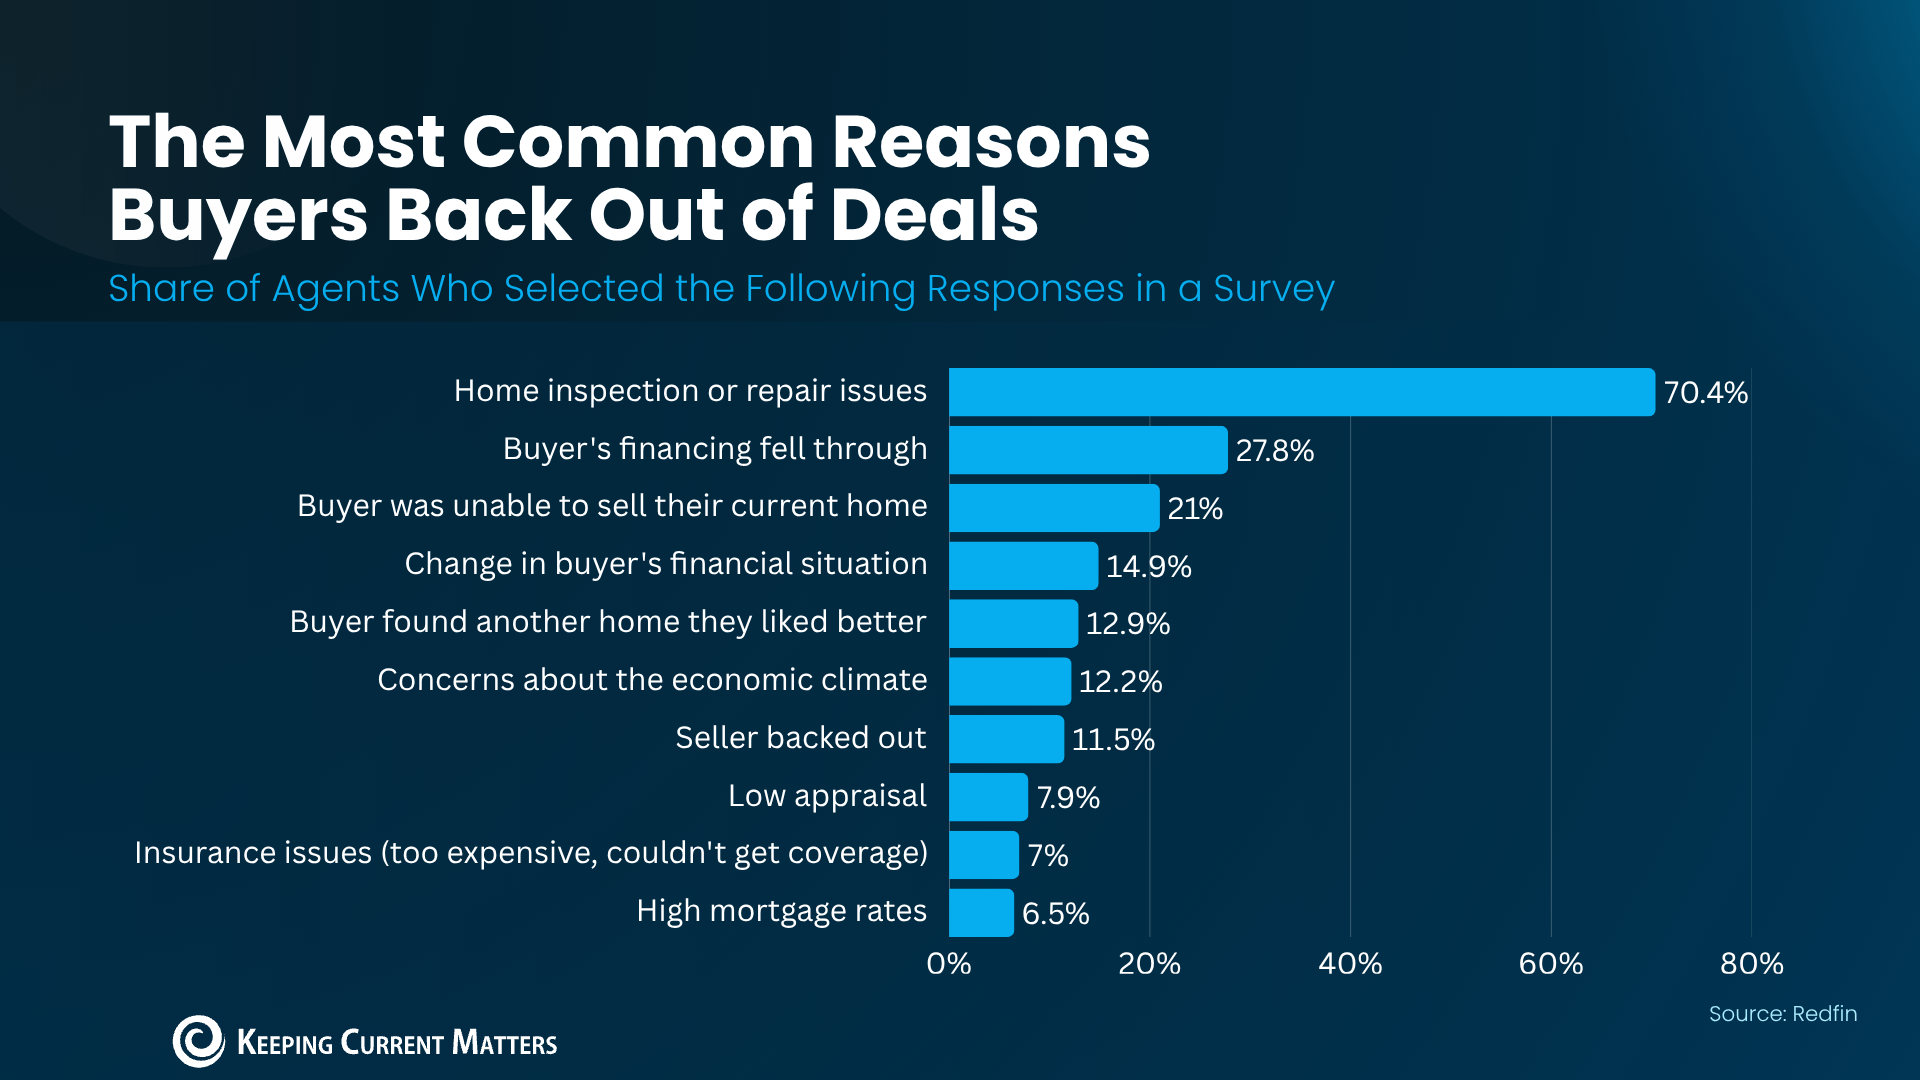
Inspection or repair issues: 70.4% of agents. Buyer financing fell through: 27.8%. The buyer could not sell their current home: 21%.
High mortgage rates on their own? Just 6.5%.
That last number matters. Buyers are not walking away over the rate headline. They are walking away over something specific to the house, or to their own file.
Specific problems have specific fixes.
What the Headlines Always Leave Out.
The headline counts the canceled deals. It does not tell you which ones were preventable.
Most of them were.
Inspection surprises are a preparation problem. If the buyer’s inspector finds the roof issue first, the buyer controls that conversation. If you find it first, you control it. A pre-listing inspection lets you fix it, price for it, or disclose it up front.
Financing failures are a vetting problem. This is my side of the table. A buyer whose approval only works at today’s rate, with no lock and no room, is one rate move away from walking.
Here is what that looks like.
Say a couple earns $11,000 a month gross and carries $500 a month in other debt. They are buying with a $405,000 loan. Taxes and insurance run $650 a month.
At 6.82%, their total house payment is about $3,296. That is 30% of their gross income. Their total debt-to-income ratio is 34.5%.
Before they lock, rates rise half a point to 7.32%. The payment climbs about $136 a month, to roughly $3,432.
Now housing is 31.2% of their income. Total DTI is 35.7%.
One half-point move pushed them past both of my guardrails. Some loan programs will still approve that file. It is still a stretch, and stretched buyers walk.
Home-sale contingencies are a timing problem. If your buyer has to sell first, your closing depends on their sale. You need to know where that sale stands before you accept.
None of that gets fixed by waiting another season. It gets fixed by preparing.
What This Means For Your Plan.
If you are selling:
Start before the listing goes live. Ask your agent whether a pre-listing inspection makes sense for your house. Know your condition issues before a buyer does.
When offers come in, look past the price. Have your agent find out three things. Is the buyer fully pre-approved, or only pre-qualified? Have they locked a rate, or are they floating? Is there a home-sale contingency, and if so, is their house listed, under contract, or not on the market yet?
The highest price is not always the strongest offer. A buyer with a locked rate and room in their numbers is worth weighing against a bigger number from a buyer with neither.
Then decide where incentives fit. A closing cost credit or a rate buydown helps a buyer near the edge stay in the deal. If you want to see how rate decisions move a payment, my breakdown on what you can control about your mortgage rate walks through it.
And know your own position before you negotiate. My guide on what your house is really worth for your next move shows you how to find it.
If you are buying:
Do not be the buyer who backs out.
Get fully pre-approved, with your income and assets documented, before you shop. Lock your rate once you are under contract. Do not open new credit, finance furniture, or change jobs before closing.
Then hold your numbers to the guardrails. Under Rule 8 in our system, keep your total DTI at 35% or less. Under Rule 9, keep your housing expense at 30% of gross income, including principal, interest, taxes, and insurance. Under Rule 3, use no more than 10% of your credit limit and pay it off every month.
A file with room in it survives a rate move.
If you are selling and buying at the same time:
Your sale and your purchase are now linked. If your buyer backs out, both deals feel it.
Under Rule 12 in our system, have a fully funded emergency fund of 6 to 12 months of expenses before you take on the chance of carrying two payments. The timing questions are in my guide on whether to buy first or sell first.
Read your buyer’s financing the way a lender would.
Before you accept, we can walk through what to ask about the buyer’s pre-approval, rate lock, and contingencies, and what a credit or buydown would actually do to their payment.
Talk With PatThe Question You Should Be Asking Together Right Now.
Not, what if the buyer backs out?
The better question is: have we done everything we can to make our house the easy one to close on?
Answer that together before you list.
Ask your agent about a pre-listing inspection. Fix it, price for it, or disclose it before a buyer finds it.
Full pre-approval. Rate lock status. Any home-sale contingency, and exactly where that sale stands.
Your equity, your next payment, and a full emergency fund if you are selling and buying at the same time.
Put it on the agenda for your next Money Meeting. Rule 10 in our system is meeting at least twice a month. Make this one of them.
My wife and I have watched this market move through every kind of cycle in 34 years of marriage and real estate. The sellers who came out ahead were not the ones waiting for zero risk. They were the ones who prepared for the risk they could see.
Bottom Line
Canceled contracts are up. Cotality reported the highest August cancellation rate in 5 years. That is real.
But most deals still close. The ones that fall apart usually fall apart for reasons you can see coming: the inspection, the financing, or a home the buyer could not sell.
Do not let the fear of a buyer backing out set your timeline. Prepare for it, and sell on your terms.
Your next step: ask your agent about a pre-listing inspection this week, then talk it through with me so you know how to read the financing on any offer you get.
Pat Collins, Mortgage Advisor | NMLS #1628553
34 Years of Marriage and Real Estate — I have been on both sides of every table.
Educational disclosure: This article is for general educational purposes and is not individualized mortgage, financial, legal, tax, insurance, credit, investment, or real estate advice. It is not a loan offer, a rate quote, or a commitment to lend. Loan qualification, rate lock terms, debt-to-income limits, and program guidelines vary by borrower, property, loan program, lender, market, and timing. Contract terms, contingencies, inspection rights, and disclosure obligations vary by state and by contract; confirm them with your real estate agent and, where needed, a real estate attorney. Seller credits and rate buydowns are subject to loan program limits. Examples are hypothetical and rounded, and the payment example assumes a 30-year fixed loan. Review current written terms with the appropriate licensed professionals before making a decision.
Reference sources: Keeping Current Matters — “Don’t Let the Fear of a Buyer Backing Out Scare You Away from Selling”, October 29, 2026. Cancellation data from Cotality, “10 things to know about the property market: September 2026”, September 24, 2026. Agent survey from Redfin, conducted September 2025. Rate data from Freddie Mac PMMS, week ending October 22, 2026.
Pat Collins
I have spent decades in business, sales, real estate, and helping people solve problems. My goal is to help homeowners and buyers read the numbers behind every offer, from the inspection to the financing, so the deal they sign is the deal that closes.